Posts

New Updates for Job Work and Restaurant Service GST Tax Rates has been changed W.E.F. 1.10.2019
Image
Nature of service Old Rates New Rates Job work service for Diamond   5 % 1.5 % Job work service for Bus Body Building 18 % 18 % Job work service for Engineering related service (other than Bus Body Building service ) 18 % 12 % Supply of Hotel Accommodation having value of supply of unit more than 1000 but less than 7500 or equivalent 12 % Supply of Restaurant service other than ‘specified premises ‘ (provided without input) 5 % Supply of goods, being food , any other article for human consumption or any drink by Indian Railway or IRCTC or their licensee whether in train or platforms. (provided without input ) 5 % Supply of “ outdoor Catering” at premises other than “specified premises”   (provided without input) 5 % Composite supply of “outdoor catering” together with renting of premises other than ‘ spec...
IMPORTANT NEWS FOR THE DEALERS E WAY BILL WILL BE GOING TO BLOCK FROM 21ST NOVEMBER 2019

IMPORTANT NEWS FOR THE DEALERS E WAY BILL WILL BE GOING TO BLOCK FROM 21ST NOVEMBER 2019  E way bill mandatory if you move goods of Rs 50,000 or more . if any dealer, who has not filled two consecutive tax figure return for any reason then his E way bill will be going to block on GST Site from 21st November 2019.    I would like to inform all the dealers kindly update your return till now .                                                                     Author                                                                                            ...

CORPORATE TAX RATE REDUCED TO 22% AND 15% AND OTHER FISCAL RELIEF IN CONNECTION TO CAPITAL GAIN

Image
The Government has made some some certain Amendments in the Income Tax Act 1961 “The Act” and the Finance Act 2019. 1. FOR DOMESTICE COMPANIES -  Anew provision has been inserted in the Income Tax Act with effect from FY 2019-20. Which allows an option to pay income – tax at the rate of 22% . The effective tax rate for these companies shall be 25.17% inclusive of surcharge & cess. Also , such companies shall not be required to Pay Minimum Alternate Tax (MAT).             CONDITION            Domestic Company will not avail any exemption / incentive. 2. NEW DOMESTICE MANUFACTURING COMPANIES (Incorporate on or after 1st October 2019)   Another new provision has been inserted in the Income Tax Act with effect from FY 2019-20 allows an option to pay Income Tax at the rate of 15 % . the effective tax rate for these companies shall be 17 .01% inclusive of surcharge & cess . Also , such company...

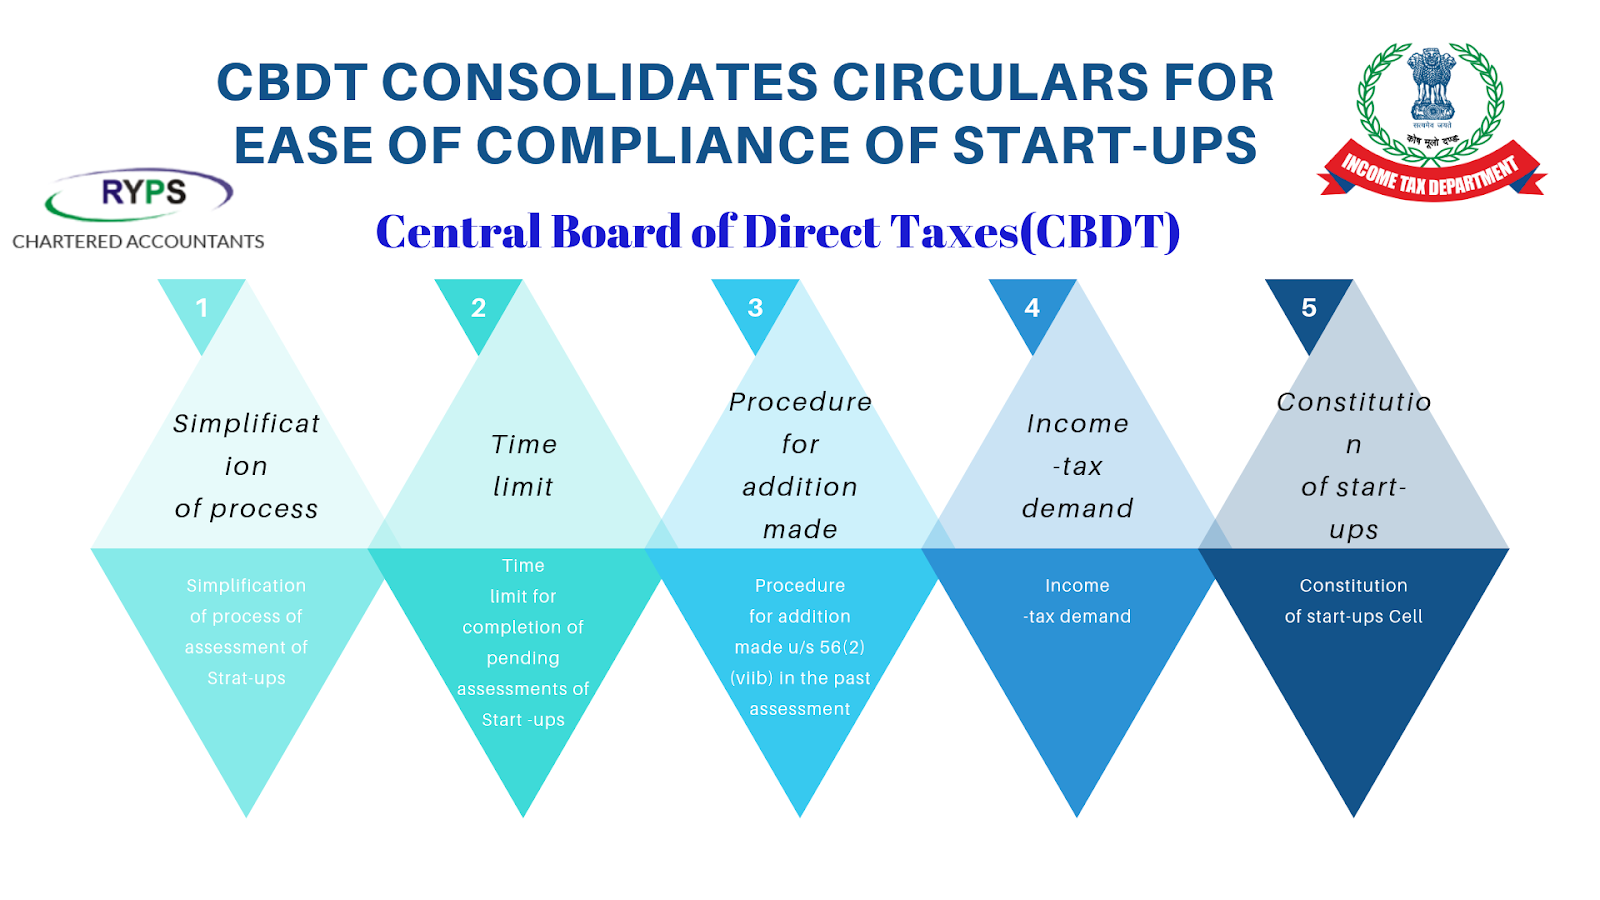
CBDT CONSOLIDATES CIRCULARS FOR EASE OF COMPLIANCE OF START-UPS

Image
In order to provide hassle -free tax environment to the Start-ups. CBDT issued various circulars / clarifications on a series of announcement  have been made by Finance Minister Smt. Nirmala Sitharaman in her General Budget 2019 and also on 23rd August 2019. The present circular inter alia highlights the following: - i) Simplification of process of assessment of Strat-ups – Circular No 16/2019 dated 7th of August 2019 provide for the simplified procedure of assessment of Start-ups recognized by DPIIT . the circular covered cases under “limited scrutiny “, cases where multiple issues including issue of section 56(2)(viib) were involved or cases where Form No 2was not filed by the start-ups entities. ii) Time limit for completion of pending assessments of Start -ups: All cases involving “ limited scrutiny “ were to be completed preferably by 30th September 2019 and the other cases of start-ups were to be disposed off on priority preferably by 31st October 2019. iii) Proc...

REVERSE CHARGE MECHANISUM UNDER GST

Image
Meaning Generally, the supplier of Goods & Services is liable to pay GST (supplier collect tax from buyer and pay tax to Govt. on behalf of buyer). But under RCM GST is paid by recipient of Goods & Services (under RCM buyer directly pay tax to Govt.) Type of RCM There are two types of cases for which RCM is mandatory 1.        Covered under section 9(3) of CGST/SGST (UTGST)Act and section 5(3) of IGST Act. supply Goods or Services or both notified by the Government 2.        Covered under section 9(4) of CGST/SGST (UTGST) Act and section 5(4) of IGST Act. Supply of taxable Goods or Services or both by an unregistered supplier to a registered supplier.    Registration If RCM is applicable to a person, then GST registration is mandatory. At that time threshold limit of Rs 10/20/40/ lacs will not be applicable to them ITC ...

GET RID OF PENALTY, FINE, INTEREST, AND PROSECUTION UNDER CENTRAL EXCISE AND SERVICE TAX

Image
In the Union Budget 2019-20, The Hon’ble Finance Minister announced the SABKA VISHWAS – LEGACY DISPUTE RESOLUTION SCHEME 2019 , The Scheme has now been notified and will be operationalized from 1st September 2019. The scheme would continue till 31st December 2019. PURPOSE  The dispute resolution component is aimed at liquidating the legacy cases of Central Excise and Services Tax that are subsumed in GST and are pending in litigation at various forums. The object of this scheme is to free as large segment of taxpayers from the legacy taxes as possible. COMPONENTS  There are two main components of the scheme are dispute resolution and amnesty. The amnesty component of the scheme offers an opportunity to the taxpayers to pay the outstanding tax and be free of any other consequence under the law. it provides substantial relief in tax dues for all categories of cases as well as full waiver of interest, fine, penalty, there is also complete amnesty from prosecution. ...

BE AWARE ABOUT TAX INVOICE FIELDS UNDER GST REGIME

Image
 BUSINESS STRUCTURE   i) Registered Dealer                                                                  -   Tax invoice ii) Composite Dealer/ Exclusive exempted supply dealer         -   Bill of Supply iii) Unregistered Dealer                                                               -   NA TAX INVOICE    When Issued      Supply of Goods & Services      Purchases of Goods & Services under Reverse Charge Rules If sale to Unregistered Dealer i) No need to issue tax invoice for Supply of Goods & Services up to Rs 200(in case ...